Financial mathematics foundations
Financial mathematics describes cash amounts at different times. The principal is the starting amount, the interest is the change earned or charged, and the balance is the amount after the stated time.
Convert a percentage rate to a decimal before calculation: . An increase of uses multiplier ; a decrease of uses . The rate and time must refer to the same period.
With simple interest, interest is calculated only on the original principal. If the decimal rate is per year for years, then and . The balance changes linearly.
With compound interest, each period's interest is added to the balance before the next period. Interest is therefore earned or charged on earlier interest, producing geometric growth. Unless a question explicitly says simple interest, repeated percentage change normally means a compound model.
With no intervening deposits, withdrawals or fees, interest earned is the final balance minus the initial principal: . For a fully repaid, fee-free loan, total interest paid is total repayments minus the amount originally borrowed. Separate any fees or other cash flows before using these shortcuts.
Key terms
- Principal
- The initial amount invested, saved or borrowed.
- Interest
- Money earned on savings or charged for borrowing.
- Interest rate
- The proportional change per stated time period, written as a decimal in formulas.
- Term
- The total duration of an investment or loan.
- Balance
- The value of the account or debt at a specified time.
- Simple interest
- Interest calculated only on the original principal.
- Compound interest
- Interest calculated on the current balance, including previous interest.
Worked examples
Calculate simple interest
A student invests $4800 at 3.5% simple interest per year for 4 years. Find the interest and final balance.
- 1Write the rate as a decimal: .
- 2Use .
- 3Add the interest to the principal: .
Answer: The interest is $672 and the final balance is $5472.
Compare simple and compound interest
Compare $4800 invested for 4 years at 3.5% simple interest and at 3.5% compounded annually.
- 1The simple-interest balance is .
- 2The compound balance is .
- 3Compound interest earns interest on earlier interest, so it produces about more.
Answer: The compound account is worth approximately $5508.11, which is $36.11 more than the simple-interest account.
Rules and formulas
Simple interest earned
- simple interest earned or charged
- principal
- decimal rate per time unit
- number of matching time units
Simple-interest balance
- final balance
Percentage multiplier
- percentage increase or decrease
Compound interest and future value
The future value is the value of a present amount after repeated compound growth. If the periodic decimal interest rate is for periods, then . This is the nth-term formula of a geometric sequence.
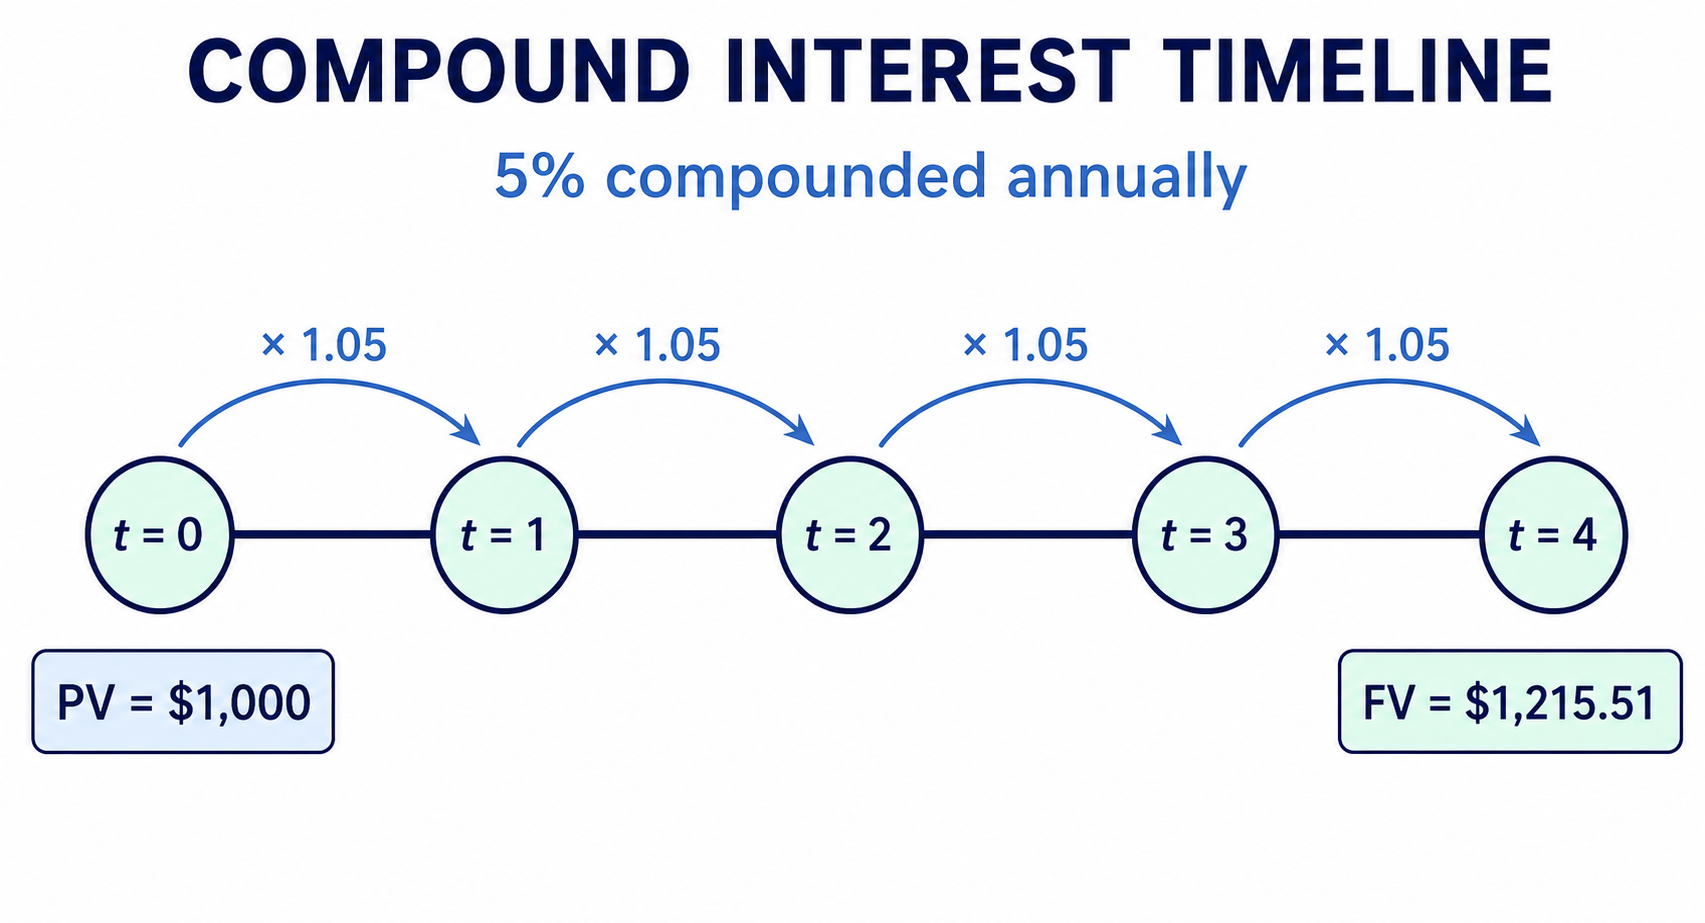 Each arrow is one compounding period. Four arrows give to the nearest cent.
When interest is compounded annually at annual rate for years, use and . For any other frequency, first convert the annual rate and time to matching periodic values.
The formula can be rearranged to find an unknown starting amount. To find a rate, isolate the power and take an nth root. To find time, use logarithms or a GDC solver because the unknown appears in an exponent.
A calculated time such as years may need contextual interpretation. If interest is credited only once per whole year and the question asks when a target is first reached, test years 11 and 12 and choose the first valid whole period.
Key terms
- Future value (FV)
- The accumulated value after interest has been applied for the stated periods.
- Present value (PV)
- The value at the starting date of the model.
- Periodic rate
- The decimal rate applied once in each compounding period.
- Compounding period
- The interval after which interest is added to the balance.
Worked examples
Find future value
$2500 is invested at 4.2% compounded annually for 6 years. Find the future value.
- 1Identify , , and .
- 2Substitute: .
- 3Evaluate using full calculator precision, then round to the nearest cent.
Answer: The future value is approximately $3199.97.
Find the compound interest rate
$6000 grows to $7500 in 5 years with annual compounding. Find the annual interest rate.
- 1Set up .
- 2Divide by 6000: .
- 3Take the fifth root: .
Answer: The annual interest rate is approximately 4.56%.
Find when an investment doubles
How long does an investment take to double at 6% compounded annually?
- 1The principal cancels: .
- 2Use logarithms: .
- 3With annual crediting, test the surrounding whole years. The balance has not doubled after 11 years but has after 12 years.
Answer: The mathematical time is about 11.90 years; the first completed annual period at or above double is year 12.
Rules and formulas
Compound future value
- future value
- present value or principal
- decimal rate per compounding period
- number of compounding periods
Periodic rate from two values
- positive compound factor; with no intervening cash flows
Number of periods
- number of periods; a whole-period target must be checked in the original inequality
Compounding frequency and effective rates
A nominal annual rate may be compounded more than once per year. If the nominal decimal rate is and there are equal compounding periods each year, then the periodic rate is . Over years, the number of periods is .
Common values are for monthly, for quarterly, for semi-annual and for daily compounding when the question specifies 365 days. Do not infer a convention that the problem does not state.
The effective annual rate is the actual percentage increase over one year after within-year compounding. For nominal rate compounded times, . More frequent compounding makes the effective rate slightly larger than the nominal rate when the nominal rate is positive.
When comparing financial products, rates must be converted to a common time basis. Comparing a nominal monthly-compounded rate directly with an effective annual rate is not a fair comparison.
Key terms
- Nominal annual rate
- A quoted annual rate divided among the stated compounding periods.
- Effective annual rate
- The actual one-year proportional growth after compounding.
- Compounding frequency
- The number of times interest is applied per year.
Worked examples
Monthly compounding
$10 000 is invested at a nominal annual rate of 6% compounded monthly for 3 years. Find its value.
- 1Monthly rate: .
- 2Number of periods: .
- 3Use .
Answer: The investment is worth approximately $11 966.81.
Convert a nominal rate to an effective annual rate
Find the effective annual rate equivalent to 6% nominal interest compounded monthly.
- 1Use .
- 2Evaluate: .
- 3Convert the decimal result to a percentage.
Answer: The effective annual rate is approximately 6.168%.
Rules and formulas
Nominal-rate compound interest
- nominal annual decimal rate
- compounding periods per year
- time in years
Periodic rate and period count
Effective annual rate
Present value and discounting
The time value of money means the same nominal amount at two different dates does not have the same financial value. Money available now can earn interest, so a future cash amount normally has a smaller present value when the discount rate is positive.
Rearranging the compound-interest formula gives . This process is called discounting. Compounding moves a value forward in time; discounting moves it backward.
For a future target, present value answers: ‘How much must be invested now?’ For a future payment, it answers: ‘What is that future cash flow worth today at the chosen rate?’ The chosen discount rate is an assumption and should match the period and context.
Key terms
- Present value
- The value today of a cash amount at another time.
- Discounting
- Moving a future value backward in time by dividing by a compound factor.
- Discount rate
- The periodic rate used to compare cash values at different times.
- Time value of money
- The principle that timing affects the value of money because money can earn a return.
Worked examples
Find the present value of a future amount
How much must be invested now at 4.5% compounded annually to have $20 000 in 5 years?
- 1Identify , , and .
- 2Discount: .
- 3Round the starting deposit to the nearest cent.
Answer: Approximately $16 049.02 must be invested now.
Present value with quarterly compounding
Find the deposit needed now to reach $15 000 in 4 years at 3.8% nominal interest compounded quarterly.
- 1Periodic rate: .
- 2Number of periods: .
- 3Use .
Answer: The required deposit is approximately $12 894.07.
Rules and formulas
Present value of one future amount
Appreciation, depreciation, growth and decay
Appreciation is repeated percentage growth in an asset's value. A rate of per period uses multiplier , so .
Reducing-balance depreciation is repeated percentage decay. A depreciation rate per period uses multiplier , so . The same percentage is applied to a smaller balance each period, so the money lost each period is not constant.
Straight-line depreciation subtracts a fixed money amount each period and is arithmetic, not geometric. Read the wording carefully: ‘loses 12% of its value each year’ is reducing-balance depreciation; ‘loses $3000 each year’ is straight-line.
A model can be rearranged to find an unknown appreciation or depreciation rate. Check that the result makes contextual sense: a depreciation rate should normally lie between 0% and 100%, and asset values from this model remain non-negative.
Key terms
- Appreciation
- An increase in value, often modelled by repeated percentage growth.
- Depreciation
- A decrease in value over time.
- Reducing-balance depreciation
- The same percentage is removed from the current value each period.
- Straight-line depreciation
- A fixed money amount is removed each period.
Worked examples
Model reducing-balance depreciation
A vehicle worth $32 000 depreciates by 18% each year. Find its value after 5 years.
- 1The retained proportion is .
- 2Use .
- 3Evaluate without rounding intermediate values.
Answer: The vehicle is worth approximately $11 863.67 after 5 years.
Model appreciation
A property valued at $280 000 appreciates by 3.2% per year. Estimate its value after 7 years.
- 1The annual multiplier is .
- 2Use .
- 3Round to a sensible currency accuracy.
Answer: The estimated value is approximately $349 072.72.
Find a depreciation rate
An asset falls in value from $45 000 to $24 000 over 6 years under reducing-balance depreciation. Find the annual depreciation rate.
- 1Set up .
- 2Then .
- 3So .
Answer: The annual depreciation rate is approximately 9.95%.
Rules and formulas
Appreciation
- decimal appreciation rate per period
Reducing-balance depreciation
- decimal depreciation rate per period
Regular savings and investments
A lump-sum investment uses one compound-interest term. Regular equal deposits form a geometric series because each deposit earns interest for a different number of periods.
For an ordinary annuity, deposits of are made at the end of each period. Immediately after the nth deposit, the future value is . The final deposit earns no interest before that valuation time. Use a positive integer payment count and a constant periodic rate . For quotient formulas assume ; at zero interest, and .
For an annuity due, the deposits are made at times . Compare both streams at the same terminal date : each due deposit then earns one extra period relative to ordinary deposits at , so multiply the ordinary future value by . This is not the value immediately after the last due deposit at .
The savings formula can be rearranged to find a regular deposit needed for a target. Deposits, compounding and the periodic rate must use the same interval. If deposits are monthly but interest is compounded annually, a more careful timeline or appropriate calculator setup is required.
Key terms
- Regular deposit
- An equal payment added to savings at fixed intervals.
- Ordinary annuity
- Equal payments made at the end of each period.
- Annuity due
- Equal payments made at the beginning of each period.
- Accumulated value
- The future value of all deposits and their earned interest.
Worked examples
Future value of monthly savings
$200 is deposited at the end of each month for 5 years into an account paying 4.8% nominal interest compounded monthly. Find the final balance.
- 1Monthly rate: . Number of deposits: .
- 2Use .
- 3The deposits total ; the rest of the balance is interest.
Answer: The final balance is approximately $13 532.04, including about $1532.04 interest.
Beginning-of-period deposits
$150 is deposited at the beginning of every month for 3 years at 3.6% nominal interest compounded monthly. Find the value at the end of 3 years.
- 1Use and .
- 2First calculate the ordinary-annuity value .
- 3Because deposits occur at the beginning, multiply by .
Answer: The annuity-due value is approximately $5710.46.
Find the monthly deposit for a target
A saver wants $25 000 after 4 years. The account pays 5% nominal interest compounded monthly, with deposits at each month-end. Find the required monthly deposit.
- 1Use and .
- 2Rearrange: .
- 3Evaluate using the unrounded periodic rate.
Answer: The required monthly deposit is approximately $471.57.
Rules and formulas
Future value of an ordinary annuity
- equal end-of-period deposit
- constant periodic rate greater than -1; zero-interest case is shown separately
- positive integer number of payments; n end-of-period deposits at times1,...,n; valued at
Future value of an annuity due
- constant periodic rate greater than -1; zero-interest case is shown separately
- positive integer number of payments; n beginning-of-period deposits at times0,...,n-1; valued at
Deposit required for a target
- constant periodic rate greater than -1; zero-interest case is shown separately
- positive integer number of payments; ordinary annuity: n end-of-period deposits; valued at
Loans, repayments and outstanding balances
An amortizing loan is repaid through equal periodic payments. Each payment first covers the interest charged on the outstanding balance; the remainder reduces the principal. Early payments often contain more interest because the balance is larger.
If is borrowed now and is paid at the end of each period for periods at periodic rate , then the loan principal equals the present value of the repayments: . Use a positive integer , equal end-of-period repayments and constant . The quotient formulas require . At zero interest, , , and .
Rearranging gives the payment formula . The outstanding balance after payments can be found by growing the original loan for periods and subtracting the accumulated value of the payments made. Use a positive integer , equal end-of-period repayments and constant . The quotient formulas require . At zero interest, , , and .
Total repayment is when every payment is equal. Total interest is , although an actual lender may adjust the final payment because regular payments are rounded to cents and may include fees not represented by the model.
Key terms
- Amortization
- Gradual repayment of a loan through scheduled payments.
- Repayment
- A periodic amount paid toward interest and principal.
- Outstanding balance
- The loan principal still owed at a specified time.
- Total interest
- Total repayments minus the original amount borrowed, excluding separate fees.
Worked examples
Calculate a monthly loan repayment
$180 000 is borrowed for 20 years at 5.4% nominal interest compounded monthly. Find the monthly repayment.
- 1Monthly rate: . Number of payments: .
- 2Use .
- 3Keep full precision before rounding the payment to cents.
Answer: The monthly repayment is approximately $1228.05.
Find the outstanding balance
For the same loan, estimate the outstanding balance immediately after 5 years, using the unrounded repayment.
- 1Five years is monthly payments.
- 2Use .
- 3Substitute the unrounded value of from the repayment calculation.
Answer: The outstanding balance is approximately $151 277.79.
Interpret total loan interest
Using the unrounded monthly repayment, estimate the total interest over the 20-year loan.
- 1Total repayment is .
- 2Subtract the original principal: .
- 3Recognize that an actual final payment may differ slightly after cent rounding.
Answer: The model gives total interest of approximately $114 732.69.
Rules and formulas
Present value of loan repayments
- constant periodic rate greater than -1; zero-interest case is shown separately
- positive integer number of payments; n equal end-of-period repayments, present value at
Periodic loan repayment
- constant periodic rate greater than -1; zero-interest case is shown separately
- positive integer number of payments; n equal end-of-period repayments of a fully amortizing loan
Outstanding balance after k payments
- balance immediately after payment k
- constant periodic rate greater than -1; zero-interest case is shown separately
- positive integer number of payments; balance immediately after payment k, where k is an integer from0 to n
Total interest on equal repayments
Inflation and the real value of money
Inflation is a general rise in prices. If prices rise by decimal rate per year, a current cost is modeled by .
The real value of a future money amount , measured in today's purchasing power, is . This is discounting by the inflation factor and is an explicit AI SL syllabus application.
To compare an investment with inflation, place both rates on a compatible effective annual basis. The exact real growth factor is , so . Subtracting rates is only an approximation.
A positive money balance does not guarantee increased purchasing power. If the effective investment return is lower than inflation, the real value falls.
Key terms
- Inflation rate
- The proportional increase in the general price level per stated period.
- Nominal value
- The amount of money stated without adjusting for inflation.
- Real value
- Purchasing power measured in the money value of a reference date.
Worked examples
Future price under inflation
An item costs now. Estimate its price after 6 years if inflation is 3% per year.
- 1Use .
- 2Evaluate: .
Answer: The estimated future price is .
Real value of future money
Find the real value today of received in 10 years if inflation averages 3.2% per year.
- 1Use .
- 2Evaluate without premature rounding: .
Answer: Its purchasing power is approximately in today's money.
Nominal return versus real return
An investment earns 5.5% effectively per year while inflation is 3.0%. Find the exact real annual return.
- 1Use .
- 2Then .
Answer: The exact real annual return is approximately 2.43%.
Rules and formulas
Future price under inflation
Real value after inflation
Exact real annual rate
Comparing financial options
Compare rates on the same effective time basis and compare cash amounts at the same date. Otherwise the comparison is not like-for-like.
For investments, consider effective return, fees, taxes, risk, liquidity and inflation. For loans, consider payment size, total interest, fees, variable-rate risk, early-repayment conditions and affordability.
A smaller loan payment does not prove a loan is cheaper: a longer term may create much more total interest. Calculate total repayments and interpret the trade-off.
A good conclusion states the mathematical advantage and at least one assumption. For example, “Option A has the larger five-year future value, assuming its rate remains fixed and fees are equal.”
Worked examples
Compare nominal and effective rates
Account A pays 5.8% nominal interest compounded monthly. Account B pays 5.9% effectively per year. Which has the higher annual return before fees?
- 1Account A has , or 5.957%.
- 2Account B has EAR 5.900%.
- 3Compare the two effective annual rates.
Answer: Account A has the higher annual return by about 0.057 percentage points, assuming the rates remain fixed and fees are equal.
Interpret a loan comparison
Loan A has a lower monthly payment than Loan B but lasts eight years longer. What must be compared before calling Loan A cheaper?
- 1Find the total of all repayments for each loan.
- 2Subtract the amount borrowed and include fees to compare total cost.
- 3Also consider affordability and rate-change risk.
Answer: Monthly payment alone is insufficient; compare total cost on a consistent basis and state assumptions.
Financial modeling workflow, assumptions and validity
Step 1: mark every cash flow and date. Step 2: select simple interest, one compound amount, depreciation, regular savings or a loan model. Step 3: match rate and period. Step 4: count periods and decide BEGIN or END timing.
Step 5: choose a formula, spreadsheet recurrence or GDC finance solver. Step 6: calculate with full precision. Step 7: check direction and approximate size. Step 8: interpret with currency, date, units and assumptions.
Financial models commonly assume a fixed rate, regular timing, no missed payments and no omitted fees or taxes. Inflation, market returns, depreciation and variable loan rates can change over time, so long extrapolations are less reliable.
A spreadsheet is useful for an amortization schedule or changing rates. Each row can show opening balance, periodic interest, payment and closing balance, making the recurrence visible.
Continuous compounding and the constant are enrichment in the current guide and are not examined here. Do not use a continuous model unless a problem explicitly defines one.
Borrowing and lending also involve affordability, transparent fees, unequal access to credit and cultural or religious views of interest. Mathematics describes consequences but does not make ethical decisions by itself.
Worked examples
Detect an unreasonable calculator result
A calculator reports for invested at a nominal annual rate of 6%, compounded monthly, for 3 years. Explain why the result must be wrong.
- 1At a positive rate, must exceed .
- 2About 18% simple growth suggests a value near , not .
- 3Check the principal, rate entry and exponent.
Answer: The order of magnitude is impossible; the correct monthly-compounded value is about .
Evaluate a depreciation model
A four-year constant-percentage model is used to predict a car’s value after 20 years. Give two limitations.
- 1The annual depreciation rate is unlikely to remain constant for 20 years.
- 2Condition, mileage, repairs, scarcity and a scrap-value floor are ignored.
Answer: The model may be useful short-term but its long extrapolation is unreliable without additional constraints.
Financial calculator and GDC methods
Many GDCs provide a TVM or financial solver. Typical fields are (number of periods), (nominal annual percentage rate), , , , (payments per year) and (compounding periods per year). Labels differ by calculator, so know your approved model's menu.
Use a consistent cash-flow sign convention. Money received and money paid must have opposite signs. For a loan, the amount borrowed may be positive and repayments negative. For savings, deposits may be negative and the future value positive. If all cash flows have the same sign, the calculator may report an error or a meaningless result.
Set and deliberately. A monthly loan normally has both set to 12; annual lump-sum growth normally uses 1. Check whether the calculator expects as a percentage such as 5.4 or as a decimal—TVM solvers usually use percentage form.
For hand calculations and GDC methods alike, show the model, identify values and interpret the output. Calculator screens do not replace mathematical communication. Restore changed financial settings after the problem so they do not affect later work.
Key terms
- TVM solver
- A calculator tool for time-value-of-money variables.
- P/Y
- Number of payments per year in a financial calculator.
- C/Y
- Number of compounding periods per year in a financial calculator.
- Cash-flow sign convention
- Money entering and leaving an account is entered with opposite signs.
- END mode
- Payments occur at the end of each period, matching ordinary-annuity formulas.
- BEGIN mode
- Payments occur at the beginning of each period, matching an annuity due.
Worked examples
GDC setup for a loan payment
Set up a TVM solver for the $180 000, 20-year, 5.4% monthly loan.
- 1Choose END mode and set .
- 2Enter , , , and .
- 3Solve for . With the loan entered as positive, the repayment appears negative because it is money paid out.
Answer: The GDC returns ; the repayment amount is $1228.05 per month.
GDC setup for an unknown investment rate
$6000 grows to $7500 over 5 years with annual compounding. Describe a TVM setup to find the rate.
- 1Set , , and .
- 2Enter and so the cash flows have opposite signs.
- 3Solve for .
Answer: The calculator returns approximately .
Practice questions with worked solutions
Attempt each question before reading its solution. Decide first whether the situation uses simple interest, one compound amount, reducing-balance change, regular deposits or loan repayments.
For every answer, check rate-period consistency, calculator precision, money rounding, units and whether a whole-number period must be tested.
Worked examples
Practice 1 — simple interest
$7200 is invested at 4.5% simple interest per year for 3 years. Find the final balance.
- 1Use .
- 2.
Answer: The final balance is $8172.
Practice 2 — annual compound growth
$3500 is invested at 5.2% compounded annually for 8 years. Find the future value.
- 1Use .
- 2Keep full precision and round the final result to cents.
Answer: The future value is approximately $5250.42.
Practice 3 — quarterly compounding
$8000 earns 6.6% nominal interest compounded quarterly for 4 years. Find its value.
- 1Use and .
- 2.
Answer: The value is approximately $10 394.61.
Practice 4 — present value
How much must be invested now at 4% compounded annually to have $30 000 in 7 years?
- 1Use .
- 2The positive discount rate should make the present value less than $30 000.
Answer: Approximately $22 797.53 is required now.
Practice 5 — depreciation
Equipment worth $55 000 depreciates by 12% per year. Find its value after 6 years.
- 1The retained multiplier is .
- 2Use .
Answer: The equipment is worth approximately $25 542.22.
Practice 6 — find an annual rate
$9000 grows to $12 000 in 5 years with annual compounding. Find the annual rate.
- 1Set .
- 2.
Answer: The annual interest rate is approximately 5.92%.
Practice 7 — first whole year above a target
$5000 is invested at 7% compounded annually. Find the first whole year when its value exceeds $8000.
- 1The equality gives .
- 2Check: after 6 years the value is about $7503.65; after 7 years it is about $8028.91.
Answer: The investment first exceeds $8000 after 7 years.
Practice 8 — regular monthly savings
$250 is deposited at each month-end for 4 years at 4.8% nominal interest compounded monthly. Find the final balance.
- 1Use and .
- 2.
Answer: The final balance is approximately $13 200.41.
Practice 9 — monthly loan payment
$25 000 is borrowed for 4 years at 6% nominal interest compounded monthly. Find the monthly end-of-period repayment.
- 1Use and .
- 2.
Answer: The monthly repayment is approximately $587.13.
Practice 10 — compare simple and compound interest
Compare $10 000 invested for 10 years at 5% simple interest and at 5% compounded annually. How much more does compounding produce?
- 1Simple balance: .
- 2Compound balance: .
- 3Subtract the two balances.
Answer: Compounding produces approximately $1288.95 more.
Practice 11 — inflation and real value
An investment is worth after 6 years. Inflation averages 2.8% annually. Find its real value in today's money.
- 1The nominal future amount is .
- 2Discount by inflation: .
Answer: The real value is approximately in today's money.
Practice 12 — comparison and validation
Account A pays 5.8% nominal interest compounded monthly; Account B pays 5.9% effectively per year. Which gives the larger one-year return before fees?
- 1Account A has .
- 2Compare 5.9567% with 5.9000%.
- 3State the assumption that rates and fees are comparable.
Answer: Account A gives the larger one-year return, assuming both rates remain fixed and fees are equal.
Topic summary and cheat sheet
Choose a formula only after identifying the cash flows, period and payment timing. Use this sheet to check a completed solution rather than to skip the model.
Rules and formulas
Simple interest
Compound amount
Nominal compounding
Effective annual rate
Present value
Depreciation
Regular savings
Loan payment
Real value after inflation
Topic summary
- Simple interest uses and ; it is calculated only on the original principal.
- Compound interest uses , where is the periodic decimal rate and is the number of matching periods.
- An increase of uses multiplier ; a decrease uses .
- For nominal annual rate compounded times per year, use and .
- The effective annual rate is .
- Present value discounts a future amount: .
- Appreciation uses ; reducing-balance depreciation uses .
- A fixed percentage change is geometric; a fixed money change is arithmetic.
- End-of-period savings deposits have . Beginning-of-period deposits gain one extra factor . Use a positive integer payment count and a constant periodic rate . For quotient formulas assume ; at zero interest, and . Compare ordinary and due streams at the same terminal date .
- An amortizing loan payment is . Use a positive integer , equal end-of-period repayments and constant . The quotient formulas require . At zero interest, , , and .
- Outstanding loan balance must account for both accumulated interest and accumulated repayments.
- In a GDC TVM solver, cash received and cash paid use opposite signs; confirm N, I%, P/Y, C/Y and BEGIN/END mode.
- Use logarithms or a solver for unknown time, then test neighbouring whole periods when the context requires an integer.
- Keep full precision during working and round the final money value, rate or payment as requested.
- Always interpret the answer with currency, time, payment timing and any limitations of the financial model.
- Inflation models future prices with .
- The real value of future money is .
- A positive nominal return can still produce a negative real return after inflation.
- The exact real annual rate is .
- Compare rates only after converting them to the same effective time basis.
- Compare cash amounts at the same date by compounding or discounting.
- A lower loan payment can produce a higher total cost when the term is longer.
- Financial models usually assume fixed rates, regular timing and no unlisted fees or taxes.
- Long-term extrapolations are less reliable when rates or circumstances may change.
- BEGIN mode means payments occur at the start of each period; END means they occur at the end.
- For a TVM lump sum use ; for a fully repaid loan use .
- Money received and money paid must use opposite signs in a TVM solver.
- A timeline prevents off-by-one period errors.
- Estimate the direction and order of magnitude before accepting a calculator result.
- Continuous compounding is enrichment and is not examined in this topic.
- A strong conclusion gives currency, date, meaning and relevant assumptions.
- Financial decisions also require judgment about risk, affordability, access and ethics.